Welcome to our new website!

We welcome your feedback on our blogs!  Drop us a line and let us know what you think.


Oct. 14, 2026

Beech Trees in Antarctica & Rising Interest Rates

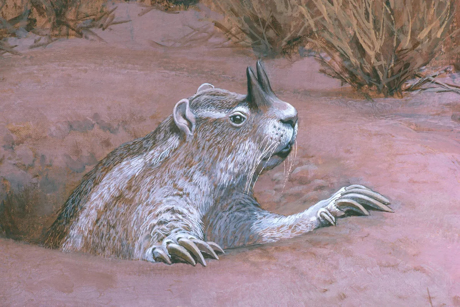
Your HOA doesn't have to worry about the extinct horn gopher!

The average 30-yr fixed interest rate for mortgages hit 7.47% in October, the highest since 2023. Government policy along with business and demographic cycles continue to make housing affordability challenging, but these conditions can change, and in short order. Homeowners can refinance mortgages.

Carbon dioxide hit 428 ppm in August 2026. The last time CO2 was ~400 ppm was 3 million years ago - beech trees grew in Antarctica and the oceans were 65 feet higher. Human culture grew out of a climate when CO2 was ~280 ppm. While adaptation to and mitigation of climate change is very possible, it is anticipated that if we can get CO2 levels to start declining by 2050 (i.e., the “Middle of the Road” scenario) we can keep global temperatures below 3C but temperatures will still be rising beyond 2100.

Though current conditions are not like 3 mya (the Pliocene), the Earth is moving toward equilibrium with the climate humans have created. Very regrettably, some houses are in the way.

The changing climate and its associated risks are affecting the financials of the real estate market – severe weather events can have a larger impact on your Return On Investment than a 7.5% interest rate. I designed the Landscape Asset and Risk Analysis (LARA) to capture these dynamics to inform local real estate investment decisions and to maximize ROI.

One example of price effects in other markets comes from Miami, FL. The Little Havana neighborhood provides homes with lower flooding risk, and enjoy greater price appreciation. Other studies show how home buyers perceive flooding risk can vary greatly regionally, and that house price response to climate disasters can decrease over time. If property with greater environmental risk has a price discount, this will regrettably attract those looking for affordable options, especially in lifestyle communities such as Asheville NC.

While LARA is a powerful tool for understanding the housing market and climate adaption, we feel it critical to support community initiatives in affordability. Affordable housing projects that use public subsidies employ more rigorous environmental due diligence than what the average home buyer uses. We offer LARA to all our real estate clients regardless of income.

Another strategy to support housing affordability is a Community Land Trusts (CLT). To minimize gentrification of low climate risk areas, CLT’s will buy many properties as a non-profit. This requires some mix of grants, financial or land donations. It is a flexible strategy that can focus on single family, multi-family or mixed-use projects. Once owned by the CLT, the homes are sold to buyers but they lease the ground from the CLT. This significantly decreases the cost of home buying while providing equity in the house.

The historically most successful CLT is the Dudley Street Neighborhood Initiative in Boston, MA, founded in 1993 to keep communities together in the face of gentrification and urban renewal. The Houston CLT was founded in 2018 to create affordable and sustainable housing after Hurricane Harvey.

As heat, drought, wildfire, flooding, and severe storms affect home owners, those pricing real estate may not understand these factors. Therefore, homes more resilient in the face of climate change maybe underpriced and homes vulnerable to climate change may be over priced. There are deals to be had and deals to avoid!

While the macroeconomic conditions in the USA will continue to change, pricing landscape attributes (e.g., parks, floodplains, etc…), not just energy efficient construction and appliances, will help stabilize the real estate market. Luckily nature is happy to tell us how to invest sustainability, we just have to listen. Reach out to learn about how LARA is able to listen to nature in the shifting market.

Thanks for reading! Click HERE to subscribe for free to receive new posts and support my work.

Doug Bruggeman   Phd, Broker/Realtor®   Blue Ridge Properties Group

Oct. 2, 2026

Fall Home Maintenance Tips: Protect Your Home Before Winter


Fall home maintenance in Western North Carolina is more than just raking leaves. Before winter weather arrives, homeowners should take time to clear leaves and limbs, clean gutters, inspect the roof, and address potential drainage and moisture problems.

Those colorful fall leaves may be beautiful, but when they pile up on your roof, clog your gutters, or collect around your home's foundation, they can create expensive problems.

Here are some of the most important fall home maintenance tasks to tackle before winter.

1. Clean Your Gutters

Falling leaves, pine needles, and small branches can quickly clog gutters and downspouts. When water can't drain properly, it may overflow along your roofline or collect around your home's foundation.

Clogged gutters can contribute to:

  • Roof and fascia damage
  • Rot around soffits and trim
  • Water intrusion
  • Basement or crawlspace moisture
  • Foundation drainage problems
  • Damaged landscaping
  • Ice buildup during freezing temperatures

Make sure gutters and downspouts are clear and that water is being directed away from the foundation.

2. Remove Leaves and Limbs From Your Roof

Leaves and other organic debris can accumulate in roof valleys, around chimneys, and beneath overhanging trees.

When wet leaves remain on a roof, they can trap moisture against roofing materials and contribute to deterioration. Large branches can also damage shingles, flashing, gutters, or the roof structure if they fall during a storm.

Never climb onto a roof if you're not comfortable doing so. A professional roof inspection or maintenance service can be a safer option.

3. Inspect Trees Around Your Home

Western North Carolina's fall and winter weather can bring strong winds, heavy rain, and occasionally ice. Dead or weakened limbs become potential hazards when they're located over your home, driveway, deck, vehicles, or power lines.

Look for dead branches, leaning trees, cracked limbs, and trees that appear unstable. If you're concerned about a tree, consider having it evaluated by a qualified arborist.

4. Check Your Roof and Exterior

Fall is a good time to look for signs of damage before winter weather makes repairs more difficult.

Check for:

  • Missing or damaged shingles
  • Loose flashing
  • Damaged gutters
  • Cracked or deteriorating caulk
  • Damaged siding
  • Peeling paint
  • Foundation cracks
  • Signs of water intrusion
  • Areas where water is pooling

Small problems are generally easier to address before they become larger ones.

5. Check Around Your Foundation

Take a walk around your home after a good rain and see where the water goes.

Make sure downspouts are directing water away from the house and look for areas where water is pooling against the foundation. Leaves and debris can also block drains and obscure drainage problems.

If your crawlspace or basement has experienced moisture issues in the past, fall is a particularly good time to make sure your drainage system is functioning properly.

6. Don't Forget Your Chimney and Fireplace

If you use a wood-burning fireplace, have your chimney inspected and cleaned as recommended by a qualified professional.

Also check your chimney cap and look for signs of water intrusion around the chimney inside the home.

7. Prepare for Colder Temperatures

Before temperatures drop, check your heating system and replace HVAC filters as recommended.

It's also a good idea to locate your home's main water shutoff and make sure exposed pipes in vulnerable areas are properly protected.

Why Fall Maintenance Matters When You're Selling

Deferred maintenance can become particularly important when you're preparing to sell your home.

A buyer who sees overflowing gutters, damaged shingles, dead limbs, or obvious drainage problems may wonder what other maintenance has been postponed. Addressing these issues before listing can help your home make a stronger first impression and reduce potential surprises during the transaction.

Frequently Asked Questions About Fall Home Maintenance

How often should I clean my gutters?

At minimum, gutters should be inspected and cleaned regularly during seasons when leaves are falling. Homes surrounded by mature trees may require more frequent attention.

Can leaves damage a roof?

Leaves and organic debris can trap moisture against roofing materials and contribute to deterioration over time. They can also clog roof drainage areas and gutters, preventing water from flowing properly.

Are fallen branches a threat to my house?

Yes. Large or weakened branches can damage roofs, gutters, siding, vehicles, decks, and other structures when they fall, particularly during high winds or severe weather.

How can I prevent water from collecting around my foundation?

Keep gutters and downspouts clear, make sure downspouts direct water away from the house, and monitor areas around the foundation for standing water or poor drainage.

What should I do before selling my home in the fall?

Start with the basics: clean the gutters, inspect the roof, address visible exterior repairs, trim potentially hazardous limbs, and make sure drainage systems are functioning properly. A pre-listing evaluation can also help identify maintenance items worth addressing before your home goes on the market.

Fall Is a Good Time to Take Care of the Little Things

A little preventative maintenance can go a long way toward protecting your home from moisture, storm damage, and winter weather.

So before you settle in for those cozy fall evenings, take a walk around the outside of your house. Look up at the roof, check those gutters, inspect the trees, and make sure water has somewhere to go.

Your house will thank you, and you'll have one less thing to worry about when winter arrives.

Thinking about selling your Western North Carolina home? Blue Ridge Properties Group is happy to help you understand which maintenance items may be worth addressing before you list.

Sept. 25, 2026

How to “Rate-Proof” Your Homebuying Budget


If you’re thinking about buying a home in the next few months, or even a year from now, one of the biggest question marks may be the mortgage rate you’ll actually get.

Mortgage rates can move significantly over time, and that uncertainty can make it difficult to know how much home you should realistically be shopping for. A recent Realtor.com study offers a useful way for buyers to plan for that uncertainty without letting changing rates completely derail their housing budget.

Plan for a Range, Not a Single Rate

Rather than assuming today’s mortgage rate will still be available when you’re ready to buy, Realtor.com recommends building some flexibility into your budget based on how far away your purchase may be.

Researchers looked at historical changes in 30-year fixed mortgage rates since 2000 and developed ranges that captured roughly 80% of historical rate movements:

  • 12 months before buying: Plan for today's rate to move up or down 1 percentage point

  • 6 months before buying: Plan for a movement of up or down 0.75 percentage points

  • 3 months before buying: Plan for a movement of up or down 0.50 percentage points

The closer you get to purchasing, the narrower the range becomes.

What Could That Mean for Your Purchasing Power?

Mortgage rates can have a surprisingly large effect on how much you can borrow while keeping the same monthly payment.

For example, using a 30-year fixed mortgage rate of 7.19% reported on September 22 as a starting point, a buyer planning to purchase in 12 months could consider a potential range of approximately 6.19% to 8.19%.

For someone with a $2,000 monthly principal-and-interest budget, that range could translate into a substantial difference in purchasing power:


Purchase Timeline Potential Rate Range Approx. Loan Range*
12 months 6.19%–8.19% $268,000–$327,000
6 months 6.44%–7.94% $274,000–$318,000
3 months 6.69%–7.69% $281,000–$310,000

*Approximate figures based on principal and interest only; taxes, insurance, HOA fees and other housing costs are not included.


In other words, a buyer who waits a year could potentially see their purchasing power change by nearly $60,000 based solely on where mortgage rates land.

That doesn't mean rates will actually move within these ranges. It simply demonstrates why planning around a single rate can leave buyers vulnerable to surprises.

What If You’re Comfortable With More Risk?

The study also calculated narrower ranges that historically captured about 50% of mortgage-rate outcomes:

  • 12 months out: today's rate ± 0.40 percentage points

  • 6 months out: today's rate ± 0.30 percentage points

  • 3 months out: today's rate ± 0.20 percentage points

This approach may make sense for buyers who are comfortable with a little more uncertainty. But the important takeaway is that your homebuying budget shouldn't necessarily be based on today's rate alone.

This Is a Planning Tool, Not a Prediction

It's important to understand what this study does and doesn't tell us.

Realtor.com's research isn't predicting where mortgage rates are headed. Instead, researchers examined historical mortgage-rate movements to give buyers a framework for thinking about potential changes.

Mortgage rates are influenced by a wide range of economic factors, and future movements are difficult to predict. Even economists who expect rates to eventually move lower acknowledge that the timing and extent of any decline are uncertain.

So, What Should Homebuyers Do?

If you're planning to buy in Western North Carolina, consider talking with a lender before you begin seriously shopping. Instead of asking only, “How much can I qualify for?” ask:

“What happens to my payment and purchasing power if the rate is 0.5%, 0.75% or 1% higher?”

Understanding those numbers can help you establish a comfortable price range rather than shopping at the very top of what you can afford.

And remember: the mortgage payment isn't the whole housing budget. Property taxes, homeowners insurance, HOA dues, maintenance and other ownership costs should all be considered when determining what feels comfortable.

Interest rates will continue to change. Your goal as a buyer doesn't have to be predicting what they'll do. Your goal can simply be making sure you're financially prepared for several possible scenarios.

If you're considering buying a home in the next few months or even next year, we're happy to help you think through the process, understand the local market and connect you with the right lending resources so you can make decisions with a little more confidence.

Sept. 17, 2026

Easement vs. Encroachment Agreement: What to Know


Buying a home in WNC often means more than finding the right house. You may also need to understand shared driveways, private roads, property boundaries, septic systems, and structures that sit close to a neighboring property.

Two terms that frequently come up during real estate transactions are easements and encroachment agreements. While both can affect how you use a property, they address different legal situations.

Understanding the difference can help buyers and sellers avoid surprises during due diligence and make more informed real estate decisions.

What Is an Easement?

An easement is a legal right to use someone else's land for a specific purpose, without owning that land. In North Carolina, an easement is an interest in real property.

For example, a property owner may have an easement that allows them to:

  • Use a shared driveway across a neighbor's property.

  • Access a landlocked parcel.

  • Install or maintain utility lines.

  • Cross another property to reach a road or other necessary access point.

Example: A shared mountain driveway

Imagine you purchase a home in Madison County that sits behind another property. The only way to reach your house is by traveling across your neighbor's driveway.

If a properly created easement grants your property the right to use that driveway, the easement establishes the legal right of access. An easement appurtenant generally benefits one parcel of land and passes with that land when it is sold.

That means the right of access is connected to the property; not simply a personal favor from the current neighbor.

Important things to know about easements

An easement does not automatically mean you can use the entire property. Its location, purpose, and conditions are determined by the applicable deed, recorded instrument, or other legal basis.

For example, a driveway easement may allow access but not give you the right to park, widen the driveway, remove trees, or install utilities unless those rights are included or otherwise established.

The takeaway: An easement establishes a right to use land for a defined purpose. It does not transfer ownership of that land.

What Is an Encroachment Agreement?

An encroachment occurs when a structure, improvement, or other physical feature crosses onto land where it does not have the necessary legal right to be.

Common examples include:

  • A fence that extends across a property line.

  • A garage or shed that sits partially on a neighboring parcel.

  • A driveway that crosses the boundary.

  • A retaining wall or deck that extends beyond the owner's property.

  • A septic-related improvement or utility feature that crosses a boundary.

An encroachment agreement is a written arrangement addressing an existing or proposed encroachment. Depending on its terms and legal structure, it may grant permission for the encroachment to remain, establish responsibilities, or require removal under specified conditions.

Example: A fence that crosses the property line

Let's say you are buying a home in Weaverville, and the seller's backyard fence extends approximately two feet onto the neighbor's property.

The fence may have been there for years. The neighbors may have always been aware of it. But the physical location of the fence does not, by itself, establish that the seller owns the land underneath it or has a permanent right to keep the fence there.

An encroachment agreement could address the situation by documenting the fence's location and the parties' agreement about its continued existence, maintenance, or removal.

The exact rights depend on the agreement and applicable law.

Easement vs. Encroachment Agreement: The Key Difference


Easement: A right to use land

An easement creates a legal right to use another person's property for a specified purpose, such as access or utilities.


Encroachment agreement: Permission or terms for an encroachment

An encroachment agreement addresses a physical improvement or use that crosses a property boundary and establishes what the parties have agreed to do about it.


An easement and an encroachment agreement can sometimes exist together. For instance, a driveway may cross an easement area, and the parties may need a separate agreement to address a particular structure or improvement.


Why This Matters When Buying a Home in WNC

In the mountains, property boundaries and access arrangements can be particularly important. A home may have a beautiful driveway, a detached garage or a useful outbuilding, but what matters is whether the legal documents support the way the property is being used.

Here are some situations where buyers should pay close attention.

1. Shared driveways and private roads

A shared driveway may involve an easement, a private road maintenance agreement, or both.

Questions to ask:

  • Who has the legal right to use the driveway?

  • Is the easement recorded?

  • Who is responsible for maintenance and repairs?

  • Are there restrictions on parking, gates, or improvements?

  • Does the legal description match the actual driveway location?

A driveway that has been used for decades is not necessarily the same thing as a properly documented easement.

2. Fences and property boundaries

A fence that crosses a property line can create questions about ownership, maintenance, and future disputes.

If a survey identifies an encroachment, the buyer should understand whether the seller has a written agreement with the neighboring property owner and what that agreement actually provides.

3. Garages, sheds, and other structures

An outbuilding may appear to be entirely on the property but extend over the boundary or into an easement.

This can matter if you plan to:

  • Expand the structure.

  • Replace or rebuild it.

  • Add a deck or porch.

  • Install utilities.

  • Sell the property in the future.

An existing structure does not automatically mean future improvements are permitted.

4. Septic systems and utility access

WNC properties frequently rely on private septic systems, wells, and shared infrastructure.

A septic drainfield, well access, or utility line may involve an easement or another legal arrangement. It is important to distinguish between the right to access or use land and the physical location of an improvement.

For example, a septic system may be located on a neighboring parcel under a recorded easement. Alternatively, a pipe or improvement may physically cross a boundary and require a separate agreement.

Do not assume that an easement for access automatically authorizes every type of construction or utility installation.

What Should Buyers Review During Due Diligence?

If you are purchasing a property and discover an easement or encroachment agreement, these are the documents and questions worth reviewing with your real estate attorney.

1. The recorded deed and easement documents

Review the legal description, location, purpose, parties, and any restrictions.

2. A current survey

Determine whether fences, structures, driveways, and other improvements cross property lines or easement areas.

3. Any encroachment agreement

Check who signed it, what it permits, whether it is recorded, and whether it binds future owners.

4. The practical responsibilities

Understand maintenance, repair, access, insurance, removal obligations, and any costs associated with the arrangement.

Questions to ask before closing

  • Is the easement or agreement recorded with the county Register of Deeds?

  • Does the document describe the actual location of the driveway, fence, or structure?

  • Does it run with the land, or is it limited to particular individuals?

  • Does it authorize the current use?

  • Could the arrangement affect future construction or resale?

  • Are there unresolved disputes with neighboring property owners?

North Carolina easement law can be fact-specific. A recorded document, survey, and the parties' actual use of the land may all matter in determining the rights involved.

What Sellers Should Know

Sellers should disclose known property issues honestly and provide relevant documents during the transaction.

If you know that a fence, shed, driveway, or other improvement crosses onto neighboring land, it is important to address the issue rather than assume it will go unnoticed.

A buyer may request:

  • A survey.

  • A copy of the easement.

  • A copy of an encroachment agreement.

  • Written clarification from the neighboring property owner.

  • An agreement to resolve the encroachment before closing.

Whether a particular document is sufficient, whether an agreement must be recorded, and whether a particular encroachment can remain are legal questions. Sellers should consult a North Carolina real estate attorney before signing a new agreement or attempting to resolve a boundary dispute.


Final Thoughts: Know What You Are Buying

An easement and an encroachment agreement may sound similar, but they serve different purposes.

An easement is generally about a legal right to use land. An encroachment agreement is about addressing a physical improvement or use that crosses a property boundary.

Both can affect access, construction, maintenance, and future ownership. That is why reviewing these documents during due diligence is an important part of buying property in Western North Carolina.

At Blue Ridge Properties Group, we believe that understanding the details of a property is just as important as falling in love with the view. Our team can help you identify questions to ask, locate relevant documents, and coordinate with the appropriate professionals as you move through the real estate process.

Thinking about buying or selling property in Western North Carolina? Contact Blue Ridge Properties Group to connect with our local real estate team.

Sept. 4, 2026

HOA Surveillance Cameras: What Home Buyers Should Know

Thinking about buying a home in an HOA community? There’s a new question you may want to add to your due-diligence checklist: Does the neighborhood use surveillance cameras or license plate readers?

Homeowners associations are increasingly turning to technology to improve neighborhood security and monitor community activity. Automatic license plate reader (ALPR) systems, including Flock Safety cameras, are appearing in more HOA-governed communities across the country.

For some homeowners, that added layer of security is a major benefit. For others, it raises important questions about privacy, data collection and who has access to information about their comings and goings.

As this technology becomes more common, understanding how an HOA uses surveillance technology can be an important part of evaluating a property before you buy.

Security Feature or Privacy Concern?

The answer may depend on the buyer.

Some HOAs view license plate reader cameras much like gated entrances, neighborhood patrols or security systems. Cameras can record license plates and vehicle characteristics as cars enter and leave a community, potentially helping with investigations involving theft, burglary, vandalism or trespassing.

For buyers who prioritize neighborhood security, that may be a welcome amenity.

But other buyers may have concerns about being monitored every time they enter or leave their neighborhood.

Questions might include:

  • Is my license plate being recorded?
  • Who owns the information?
  • How long is the data stored?
  • Who has access to the recordings?
  • Can the HOA share information with law enforcement or other organizations?
  • Can residents opt out of having their information retained?
  • Where are the cameras located?
  • Does the system monitor only HOA-owned property, or nearby public roads as well?

These aren't necessarily deal-breaker questions. But they are questions worth asking before you purchase.

HOA Documents May Not Tell the Whole Story

One of the challenges for buyers is that HOA governing documents may not specifically address newer surveillance technologies.

According to a recent report from the National Association of REALTORS®, some HOA documents are silent on the use of license plate readers and other surveillance systems. That means a buyer reviewing the standard HOA documents may not necessarily get a complete picture of what technology is being used in the community.

In some situations, the best way to find out may be to ask the HOA directly.

That's an important distinction when purchasing a home in an HOA: reviewing the covenants, conditions and restrictions (CC&Rs) is important, but so is asking questions about how the community is actually being managed today.

And It's Not Just License Plate Cameras

Technology in HOA communities is evolving quickly.

According to NAR's report, some HOAs are beginning to explore artificial intelligence tools that can monitor properties and identify potential covenant violations. Those systems could potentially flag things such as overgrown grass, trash cans left out beyond designated times or other possible violations.

The potential benefit is efficiency. Instead of relying entirely on a property manager or another homeowner to identify a violation, technology can flag an issue for review.

But how much monitoring is too much?

For homeowners, the answer may vary considerably.

What Should Buyers Ask Before Buying in an HOA?

If you're considering a home in an HOA-governed community, don't limit your investigation to the monthly dues and architectural restrictions. Consider asking:

1. Does the HOA use surveillance cameras?

Find out whether the community has security cameras, automatic license plate readers or other monitoring technology.

2. Where are the cameras located?

Are they at neighborhood entrances? Near amenities? Along roads? Understanding their locations can help you understand what is actually being monitored.

3. What information is collected?

A license plate reader may collect information about vehicles without using facial recognition, but buyers should still understand exactly what data the system records.

4. How long is information retained?

Ask about the HOA's data-retention policy and whether there is a defined period for deleting information.

5. Who can access the information?

Is access limited to HOA management? Board members? Security personnel? Law enforcement? A third-party technology company?

6. Can information be shared?

Ask whether the HOA can provide surveillance information to law enforcement or other third parties and under what circumstances.

7. Does the HOA have a written surveillance policy?

A written policy can provide considerably more clarity than simply knowing cameras exist.

8. Does the HOA use AI or automated monitoring?

This may become increasingly relevant as communities adopt technology capable of identifying potential property violations.

Why This Matters During a Real Estate Purchase

Buying a home isn't just about the house itself.

You're also buying into a community, neighborhood and set of rules. And those rules can affect how you use and experience your property.

That's particularly important with HOA communities because buyers may not discover certain policies until after they have already committed to the property.

This is where having an experienced real estate professional on your side can make a difference.

A good buyer's agent shouldn't simply open the door and point out the granite countertops. They should help you identify the questions that need to be answered before you move forward.

That can include reviewing HOA documents, identifying potential restrictions, asking questions of the listing agent or HOA when appropriate, and helping you understand which issues deserve additional investigation.

What About HOAs in Western North Carolina?

HOAs are common throughout the Asheville area and Western North Carolina, from established neighborhoods around Asheville and Weaverville to newer communities throughout Buncombe, Madison, Henderson and surrounding counties.

Security cameras and license plate readers may not be a deciding factor for most buyers today, but technology is changing quickly.

For one buyer, a camera at the neighborhood entrance might mean peace of mind.

For another, it might feel like an invasion of privacy.

Neither perspective is necessarily right or wrong. The important thing is knowing what you're buying into and deciding whether the community's policies fit your priorities.

Buying a Home in Western North Carolina?

At Blue Ridge Properties Group, we believe buying a home is about more than finding the right house. It's about finding the right community, neighborhood and lifestyle for you.

If you're considering an HOA property in Asheville, Weaverville or elsewhere in WNC, we're here to help you ask the right questions and do your homework before you make a decision.

Have questions about buying a home in an HOA? Contact Blue Ridge Properties Group and let's talk about what you should know before you buy.

Read the full article from the National Association of REALTORS® HERE.

Aug. 28, 2026

Appraisals Are Changing: What Buyers and Sellers in Western NC Need to Know

If you’ve bought or sold a home before, you probably have a general idea of what an appraisal looks like: an appraiser visits the property, reviews comparable sales, evaluates the home’s condition and features, and produces a report for the lender.

But the appraisal process is getting a major technological makeover. The changes could be especially important in a market like Western North Carolina where homes can be anything but cookie-cutter.

A New Era for Home Appraisals

Fannie Mae and Freddie Mac are transitioning to a new appraisal reporting system called Uniform Appraisal Dataset 3.6, or UAD 3.6.

The goal is to modernize the appraisal process, create more consistent data, and make appraisal reports easier for lenders and other professionals to understand.

The transition began in 2025, and UAD 3.6 becomes mandatory for Fannie Mae and Freddie Mac loans beginning November 2, 2026.

Instead of relying on traditional, rigid appraisal forms, the new system uses a dynamic report that can expand based on the characteristics of the property.

That matters.

A mountain home with an accessory dwelling unit, detached workshop, finished basement, acreage, solar panels, extensive renovations, or other unique features may require substantially more explanation than a standard suburban home.

The new reporting format is designed to capture more of those details.

What Will Be Different?

Under UAD 3.6, appraisal reports will contain significantly more property-specific information.

The report will provide more detailed information about:

  • Interior and exterior condition

  • Quality of construction

  • Property characteristics

  • Renovations and improvements

  • Accessory dwelling units

  • Photos and descriptive commentary

  • Property-specific features that may affect marketability

  • Comparable sales and their characteristics

The format is also designed to be more flexible. For example, if a property has an ADU, the report can generate a specific section for the appraiser to provide additional information. If the property doesn't have one, that section doesn't need to appear.

In other words, the appraisal report becomes more tailored to the property instead of forcing every property into the same box.

Why This Matters in Western North Carolina

This is where things get particularly interesting for our region.

Western North Carolina is full of properties that don't fit neatly into a standard suburban appraisal model.

Think:

Mountain homes. Acreage. Older homes. Historic properties. ADUs. Guest houses. Finished basements. Detached workshops. Multiple structures. Steep terrain. Long-range views. Renovations. Solar systems. Wells and septic systems.

Two homes with the same bedroom and bathroom count may have dramatically different market appeal, and dramatically different contributory value, because of these characteristics.

That makes accurate property data increasingly important.

A seller's agent who provides an appraiser with clear, accurate information about improvements and unique features can help make sure those characteristics are properly considered.

Realtors® Will Have an Important Role

One of the biggest takeaways from the transition isn't simply that appraisers are getting new technology.

It's that real estate agents and appraisers will need to communicate effectively.

NAR notes that the increased number of data points required by UAD 3.6 makes information provided by agents even more important. Having relevant property information available upfront can help appraisers complete their work efficiently and potentially avoid delays or additional trips to the property.

For listing agents, that means being prepared to provide useful documentation (not just a pretty listing sheet).

That could include:

  • A detailed list of improvements

  • Dates and costs of major renovations

  • Information about additions

  • Permits when applicable

  • Details about ADUs or secondary structures

  • Solar installations

  • Finished living areas

  • Recent comparable sales that help explain the market

  • Documentation supporting unusual or significant features

This doesn't mean an agent tells an appraiser what a property "should" appraise for.

It means making sure the appraiser has accurate information about the property and the market.

What Does This Mean for Sellers?

For sellers, the lesson is simple:

Documentation matters.

If you've invested $150,000 in renovations over the last several years, don't assume an appraiser will automatically know exactly what was done or when it was completed.

Keep records.

Receipts, permits, contractor invoices, surveys, floor plans, renovation documentation, and other relevant information can help tell the story of the property.

This is particularly important for unique Western NC properties where the features that make a home desirable may not be immediately apparent from traditional property data.

What Does This Mean for Buyers?

For buyers, the changing appraisal process doesn't mean your appraisal will automatically come in higher or lower.

An appraisal remains an independent opinion of a property's market value.

However, more detailed reporting could provide lenders with a clearer picture of the property and its characteristics.

And when you're purchasing a property with unusual features such as an ADU, acreage, extensive renovations, or multiple structures. Your agent should be paying close attention to how those features are represented in the available property data and comparable sales.

The Bigger Picture

Real estate is becoming increasingly data-driven.

MLS systems, automated valuation models, digital records, artificial intelligence, and now modernized appraisal reporting are changing how property information is collected, analyzed, and communicated.

But technology doesn't eliminate the need for local expertise.

In a market as diverse as Western North Carolina, understanding why one property is worth more or less than another still requires context.

A mountain view isn't simply a checkbox.

An ADU isn't just another structure.

A steep driveway, private road, well, septic system, flood exposure, renovation quality, or usable acreage can have a meaningful impact on a property's marketability.

That's where experienced local real estate professionals and experienced appraisers continue to matter.

The Bottom Line

Appraisals are becoming more detailed, more data-driven, and more dynamic.

For buyers and sellers, the change shouldn't be something to fear. Instead, it's a reminder that accurate property information and knowledgeable representation matter more than ever.

And for anyone buying or selling in Western North Carolina, having an agent who understands the unique characteristics of our local market can make a real difference not only when determining a listing or offer price, but throughout the entire transaction.

The appraisal process is changing.

The best time to understand what that means for your next real estate transaction is before you're under contract.

Aug. 26, 2026

Is the Western NC Real Estate Market Correcting?

If you’ve been watching the Western North Carolina real estate market lately, you may have noticed something different.

Homes are taking longer to sell, buyers have more choices, & sellers are negotiating more. Some properties are experiencing price reductions, & buyers aren't necessarily rushing to write an offer the moment a home hits the market.

So, is the market correcting?

In a word: Yes.

But a market correction is not the same thing as a crash.

In fact, what we're seeing across much of WNC looks more like a normalization & rebalancing of the market after several years of unusually strong buyer demand.

What Exactly Is a Real Estate Market Correction?

A market correction happens when conditions move away from an extreme & begin returning toward a more sustainable balance.

In real estate, that can happen when:

  • Inventory increases

  • Buyer demand slows or becomes more selective

  • Homes take longer to sell

  • Sellers become more willing to negotiate

  • Price reductions become more common

  • Appreciation slows or prices soften in certain segments

  • Buyers gain more leverage

A correction doesn't necessarily mean home prices are falling dramatically.

Think of it this way: a correction is the market taking a breath.

During the pandemic-era housing boom, WNC experienced extraordinary demand, limited inventory & intense competition. Homes could sell quickly, sometimes with multiple offers & significant competition among buyers.

That kind of market wasn't sustainable forever.

Today's market is moving toward something much more typical: buyers are taking their time, sellers have to compete for attention, & pricing matters again.

What Are We Currently Seeing in the WNC Market?

The latest Canopy MLS data for July 2026 provides a pretty good snapshot of where things stand.

Across the Asheville Region, 985 homes closed in July, up 4.9% from the previous year. At the same time, the median sales price was $425,000, down 1.2%, while the average sales price was $535,426, down 0.5%. New listings were down 2.8%.

That combination is important.

We're not seeing sales disappear. Buyers are still buying.

Instead, we're seeing a market where buyers have become more selective & sellers have less room to simply name a price & expect the market to follow.

In the Asheville MSA specifically, July closed sales increased 7.4% year over year, while the median sales price was essentially flat at $465,000, up just 0.5%.

That's a very different picture from a housing crash.

Inventory Is Changing the Conversation

One of the biggest changes in our market is the amount of choice available to buyers.

Inventory has been building compared with the extremely tight conditions we experienced several years ago. Earlier this year, Canopy MLS reported that Asheville MSA inventory was more than 19% higher than the previous year, while months of supply had increased to 4.1 months.

By May, the four-county Asheville area had more than 3,000 homes available, with 5.4 months of supply.

That's significant because inventory changes the psychology of a market.

When buyers have very few choices, they tend to act quickly.

When buyers have options, they can compare properties, negotiate repairs & concessions, wait for a price adjustment, or simply walk away from a home that doesn't meet their expectations.

That's exactly the kind of leverage we're seeing return to the market.

Sellers Are Feeling the Shift

One of the clearest signs of a correction isn't necessarily falling prices; it's changing seller expectations.

In May, the Asheville MSA's original list-price-to-sales-price ratio was 94.4%, down 1.4% from the previous year. Canopy MLS noted that buyers were gaining more negotiating power as sellers became more flexible on pricing and concessions.

That doesn't mean every seller is accepting a low offer. It means buyers are increasingly able to negotiate.

We're seeing more conversations around:

  • Price reductions

  • Closing-cost contributions

  • Repair negotiations

  • Inspection findings

  • Rate buydowns

  • Longer due-diligence periods

  • Homes sitting on the market longer before receiving an offer

The days of pricing a home aggressively & assuming competition will push the price even higher are becoming much less reliable.

The Market Isn't Moving the Same Way Everywhere

This is especially important in Western North Carolina. There isn't one single "WNC real estate market."

Buncombe County isn't exactly the same as Madison County. Asheville isn't the same as Weaverville. A mountain property with acreage isn't the same as a downtown condo. A $350,000 home isn't competing in the same market as a $1.2 million home.

The July numbers illustrate that variation.

For example, Buncombe County recorded 350 closed sales in July, up 6.7% year over year, while its median sales price was $485,000; down 4.9%. Yancey County, meanwhile, saw closed sales increase 25%, with its median sales price up 3.5%. Waynesville's median sales price was down 12.9%, while Hendersonville's was up 3.2%.

This is why broad headlines can be misleading.

"Western NC home prices are falling" doesn't tell the whole story. Neither does "WNC home prices are rising."

The reality is much more nuanced.

So, Is This a Buyer’s Market?

Not necessarily. It's more accurate to say that the market is becoming more balanced.

A buyer's market generally means there is substantially more supply than demand, giving buyers significant negotiating power.

We're seeing more buyer leverage, but we're also seeing healthy transaction activity. In May, pending sales across the four-county Asheville area increased 22.4% year over year, while closed sales increased 6.3%.

That's not what a frozen market looks like.

Instead, we're seeing a market where good homes that are priced correctly can still attract buyers, but buyers are increasingly unwilling to overpay for homes that don't justify the price.

That's an important distinction.

What Does This Mean for Buyers?

For buyers, a correction can create opportunities that simply weren't available a few years ago.

You may have:

More choices. You're less likely to feel like you have to buy the first house you see.

More negotiating power. Depending on the property, sellers may be more open to price adjustments, repairs or concessions.

More time to think. You may not have to make an offer within hours simply to compete.

More opportunities to find the right property. Particularly at higher price points, inventory growth has given buyers substantially more choices.

But there's an important caveat:

Don't assume every property is negotiable just because the overall market is more balanced.

A well-priced home in a desirable location can still generate significant interest.

What Does This Mean for Sellers?

For sellers, the market correction doesn't mean you can't get a great price.

It means strategy matters more than it did during the frenzy.

Pricing a home correctly from day one is increasingly important. Overpricing can result in fewer showings, longer days on market and eventually a price reduction; which can make a listing look less attractive to buyers.

Presentation matters, too. Buyers have more options, so they're comparing homes more carefully.

That means sellers should be prepared to compete on:

  • Price

  • Condition

  • Presentation

  • Location

  • Terms

  • Concessions

The goal isn't necessarily to be the cheapest house on the market.

The goal is to be the house buyers believe offers the best combination of price and opportunity.

What About a 2008-Style Crash?

The current data doesn't suggest that we're simply repeating the conditions that preceded the housing crash of 2008.

Today's market is being influenced by very different factors, including mortgage rates, affordability, increased inventory, changing buyer expectations & the normalization of demand following an extraordinary period of housing activity.

A slowdown in appreciation (or even modest price declines in some areas) is not automatically a crash.

A correction can actually be a healthy part of a functioning market.

The Takeaway for Western North Carolina

The WNC housing market is changing, but "changing" doesn't mean "crashing."

We're seeing a transition from an unusually competitive seller's market toward a more balanced, more selective and more negotiable market.

Buyers have more choices, sellers have to compete, homes can take longer to sell, pricing is becoming more important, & the market is becoming increasingly local.

For buyers, that can mean more opportunity and negotiating power.

For sellers, it means the old strategy of simply putting a property on the market & waiting for multiple offers may no longer be enough.

And for both sides, it means local knowledge matters more than ever. That's where good real estate advice makes all the difference.

Aug. 12, 2026

Mold and Real Estate: What Buyers and Sellers Need to Know

Buying or selling a home is a major financial decision, and few things can create more uncertainty during a real estate transaction than discovering mold.

Mold itself isn't always a deal-breaker. But whether you're buying or selling, it is important to understand what caused it, how extensive the problem is, and whether the underlying moisture issue has been corrected.

This is especially important in Western North Carolina, where heavy rainfall, humidity, steep terrain, and older homes can all contribute to moisture-related problems.

For Home Buyers: Don't Ignore the Signs

When you're touring a home, don't just look at the finishes. Pay attention to signs that could indicate a moisture or mold problem.

Watch for:

  • Musty or unusual odors
  • Visible discoloration or suspected mold growth
  • Water stains on ceilings or walls
  • Bubbling or peeling paint
  • Warped flooring or trim
  • Damp crawlspaces or basements
  • Condensation or excessive humidity
  • Areas that appear to have been recently repaired or painted

These signs don't necessarily mean a home has a serious mold problem. They do, however, warrant further investigation.

Find the Source, Not Just the Mold

One of the most important questions for a buyer is: Why the mold is there in the first place?

Moisture can come from a roof or plumbing leak, poor drainage, foundation seepage, flooding, inadequate ventilation, or other sources. Simply cleaning visible mold without correcting the moisture problem may allow it to return.

If mold or significant moisture is discovered during due diligence, a buyer may want to consider additional evaluation by an appropriate qualified professional.

A standard home inspection can identify many signs of moisture intrusion, but buyers should understand that a general home inspection is not necessarily a comprehensive mold investigation.

For Home Sellers: Address Problems Before They Become Surprises

Sellers should not wait until an inspection uncovers a moisture or mold issue.

If you already know about a past or current moisture problem, it is worth addressing it before putting the home on the market. Depending on the circumstances, that might mean correcting a leak, improving drainage, repairing a crawlspace, replacing damaged materials, or obtaining professional mold remediation.

Taking care of the underlying issue can make the transaction smoother and give prospective buyers greater confidence.

Don't Just Cover It Up

One of the worst approaches is attempting to make evidence of a moisture problem disappear without addressing the cause.

Painting over stains, replacing a small section of drywall, or cleaning visible mold may improve the appearance, but it doesn't necessarily solve the underlying problem.

And if a buyer's inspection later uncovers evidence of previous moisture intrusion, the seller may find themselves answering even more questions than they would have if the issue had been properly addressed from the beginning.

Documentation Can Help

If a seller has had mold or moisture problems professionally addressed, keeping documentation can be extremely helpful.

Depending on the situation, useful records may include:

  • Invoices for repairs
  • Reports from contractors or remediation professionals
  • Documentation showing the source of moisture was corrected
  • Photos of the work before and after
  • Warranties or guarantees, if applicable
  • Information about materials that were removed or replaced

Having this information available can help a buyer understand what happened and what was done to correct it.

Disclosure Matters

Sellers should be forthcoming about known material facts and property conditions as required by applicable law and real estate forms.

In North Carolina, sellers should work with their real estate agent and, when appropriate, legal counsel to understand their disclosure obligations. A known moisture or mold issue shouldn't simply be ignored because the seller believes it has already been repaired.

The goal isn't to scare buyers away. It's to provide accurate information so everyone can make informed decisions.

Should a Buyer Walk Away Because of Mold?

Not necessarily.

Homes can have a history of leaks, flooding, crawlspace moisture, or other conditions that have been successfully corrected. The presence of past mold doesn't automatically mean the property is a bad investment.

The more important questions are:

What caused the problem?

How extensive was it?

Has the moisture source been corrected?

Was the affected material properly addressed?

What will it cost to maintain or prevent the problem in the future?

A buyer may decide to proceed, negotiate repairs or credits, or request additional investigation. In some cases, the extent or uncertainty of the problem may cause a buyer to reconsider the purchase.

A Little Prevention Can Go a Long Way

For both homeowners and prospective buyers, moisture prevention is one of the best defenses against mold.

Keep gutters and downspouts functioning properly, direct water away from the foundation, address leaks promptly, maintain appropriate indoor humidity, and pay attention to crawlspaces, basements, roofs, and other areas vulnerable to moisture.

In Western NC, where our homes can take a beating from rain and humidity, staying ahead of water intrusion can save homeowners considerable money and frustration.

The Bottom Line for Buyers and Sellers

For buyers, don't panic when you see mold, but don't ignore it either.

For sellers, don't simply hide evidence of a moisture problem and hope nobody notices.

In both cases, the best approach is to identify the source, determine the extent of the issue, address it appropriately, and document the work.

Mold may be a manageable problem. Unresolved moisture is the problem you don't want to inherit or leave behind.

If you're buying or selling a home and discover a potential mold or moisture issue, your real estate agent can help you navigate the transaction, while qualified inspectors, contractors, remediation professionals, and other specialists can provide the technical information needed to make an informed decision.

If you or someone you know is experiencing mold issues in their home or suspect that mold may be an underlying issue, contact us here at Blue Ridge Properties Group for a list of trusted mold remediation specialists in the area. We care about the health and safety of our community, and we are happy to help!


Aug. 7, 2026

Alternatives to a Price Reduction: How Sellers Can Attract Buyers in Asheville’s Housing Market

When a home has been sitting on the market longer than expected, the conversation often goes straight to one thing: “Should we lower the price?”

Sometimes the answer is yes. Pricing correctly is one of the most important parts of a successful sale. However, a price reduction isn't the only tool sellers have.

In today's housing market, buyers are looking closely at their monthly payment, upfront costs, condition, and overall value of the purchase. That means sellers may have other ways to make a property more appealing (or more affordable) without immediately cutting the asking price.

Here are several strategies worth discussing with your real estate agent:

1. Offer a Seller Credit Toward Closing Costs

Instead of reducing the purchase price, a seller can offer a credit toward the buyer's allowable closing costs and prepaid expenses, subject to the buyer's loan program and lender approval.

For example, instead of dropping a $500,000 listing to $485,000, a seller might offer a $15,000 credit.

Why can this be attractive?

A buyer may have enough income to qualify for the home but not enough cash available for all of the costs associated with purchasing it. A closing-cost credit can reduce the amount of money they need to bring to the closing table.

Important: Seller concessions are subject to limits and restrictions that vary by loan type and transaction. The buyer's lender should confirm what is permitted before a seller makes a credit part of the marketing strategy.

2. Consider a Temporary Mortgage Rate Buydown

A seller may be able to contribute toward a temporary interest-rate buydown, depending on the buyer's loan program and lender.

A common example is a 2-1 buydown, where the buyer's interest rate is temporarily reduced during the first two years of the loan before returning to the regular note rate.

This doesn't necessarily make the house cheaper, but it can make the monthly payment more manageable at the beginning of ownership.

For buyers who are payment-sensitive, that can be more compelling than a relatively small reduction in the purchase price.

3. Offer a Permanent Rate Buydown

Another possibility is contributing toward discount points that permanently reduce the buyer's mortgage interest rate.

This can be particularly attractive when buyers are focused on monthly affordability.

The math can get complicated, though, so sellers shouldn't assume that a rate buydown is automatically better than a price reduction. The buyer's lender can calculate the actual payment savings and explain the available options.

4. Pay for a Home Warranty

A home warranty won't make a $600,000 house suddenly affordable, but it can reduce some of the perceived risk that comes with buying a home. This can be especially useful for properties with older appliances, HVAC systems, or other components that buyers may worry about after closing.

A warranty can be a relatively inexpensive concession compared with a significant price reduction.

5. Address the Repairs Buyers Are Most Likely to Notice

Sometimes the problem isn't the price. It's the list of things buyers see when they walk through the door.

A seller doesn't necessarily need to renovate the entire house. Instead, focus on high-impact, relatively inexpensive improvements:

  • Fresh interior paint
  • Professional cleaning
  • Carpet cleaning or replacement
  • Landscaping and yard cleanup
  • Replacing dated light fixtures
  • Repairing obvious maintenance issues
  • Deep cleaning kitchens and bathrooms
  • Improving curb appeal
  • Removing excess furniture and clutter

In other words, don't spend $30,000 remodeling a kitchen if $5,000 of targeted improvements could make the home feel significantly more move-in ready.

6. Include Personal Property That Adds Appeal

Depending on the property and the transaction, sellers may be able to include items that make the home more attractive. Think:

  • Patio furniture
  • Appliances
  • A riding mower
  • Certain window treatments
  • Garage shelving
  • Outdoor equipment

The details matter, and anything included in a transaction should be clearly documented in the contract. But sometimes an item that has relatively little value to the seller can have meaningful appeal to a buyer.

7. Offer a Flexible Closing Date

Not every concession needs to involve money.

A buyer may have a home to sell, a lease that is expiring, children starting school, or another timing issue. Being flexible about the closing date, or offering a particular possession arrangement when appropriate, can make a property more attractive.

For some buyers, convenience is valuable.

8. Improve the Listing Before Changing the Price

Before reducing the price, take a hard look at how the property is being presented. Ask:

  • Do the listing photos show the home at its best?
  • Are there enough photos?
  • Does the first photo grab attention?
  • Does the description highlight the property's strongest features?
  • Is the home easy to show?
  • Are there too many restrictions on showing times?
  • Does the property look cluttered or poorly maintained online?
  • Is the listing reaching the right buyers?

Sometimes the property isn't failing; it simply isn't getting enough attention.

A new set of professional photos, improved staging, updated marketing, or a refreshed listing strategy can create a reason for buyers and agents to take another look.

9. Consider a Combination Strategy

The strongest strategy isn't always price reduction OR seller concession. Sometimes it's a combination.

For example, a seller might make a modest price adjustment while also offering a closing-cost credit or addressing a specific repair.

The goal is to create a package that feels compelling to today's buyers without unnecessarily giving away more than the seller needs to.

So, Should You Reduce the Price?

Maybe.

A price reduction can be exactly what a property needs if the home is simply overpriced compared with its competition.

But before automatically cutting the asking price, sellers should look at the bigger picture.

Are buyers objecting to the price? The monthly payment? The condition? The upfront cash required? The home's presentation?

Those are different problems, and they don't necessarily require the same solution.

In a market where buyers have choices, the goal isn't simply to have the lowest price. The goal is to make your property feel like one of the best opportunities available at its price point. That's where a thoughtful pricing and marketing strategy comes in.

Before you make a price reduction, talk with your real estate professional about all of your options. Depending on your property, buyer pool, and market conditions, a strategic concession or targeted improvement could make more sense than simply dropping the asking price.

Thinking About Selling?

At Blue Ridge Properties Group, we help sellers look at the whole picture (not just the list price) to create a strategy that gets their property noticed and gets buyers through the door.

July 29, 2026

Weaverville, NC Real Estate Market Trends: What Buyers & Sellers Need to Know

The Weaverville, NC real estate market is shifting. After several years of intense competition and rapidly rising prices, buyers now have more choices, sellers are facing more competition, and pricing correctly has become more important than ever.

A More Balanced Market

Current market data shows that Weaverville has more inventory and longer marketing times than we saw during the pandemic-era housing boom. Homes are taking longer to sell, giving buyers more opportunity to compare properties and negotiate.

That doesn't mean every home is sitting on the market. Well-priced, desirable properties can still attract strong interest, while homes that are overpriced or need significant work may take considerably longer to sell.

Buyers Have More Leverage

Today's buyers have more negotiating power than they've had in recent years. Depending on the property, buyers may be able to negotiate the price, repairs, closing costs, or other terms.

But buyers shouldn't assume every seller is willing to make a deal. Desirable homes that are priced appropriately can still move quickly.

Pricing Matters for Sellers

For sellers, overpricing can be costly.

Buyers today have more options and are paying close attention to condition, location, acreage, views, access, renovations, and overall value compared with competing properties.

A home doesn't necessarily need to be completely renovated before listing, but the asking price needs to reflect its current condition and the competition.

What Does This Mean for Weaverville?

The Weaverville market isn't crashing! It's becoming more balanced and selective.

For buyers: More inventory means more choices and greater negotiating power.

For sellers: Strategic pricing, preparation, and marketing are more important than ever.

And because real estate is incredibly local, citywide statistics only tell part of the story. A home in downtown Weaverville, a mountain property with acreage, and a suburban neighborhood home can all experience very different market conditions.

The Bottom Line

The Weaverville real estate market in 2026 is giving buyers more breathing room while requiring sellers to be more strategic.

If you're considering buying or selling in Weaverville, Asheville, or Western North Carolina, understanding what's happening in your specific neighborhood and price range is far more useful than relying on a single market statistic.

The market isn't just the market. It's your market.